Volume as Theater: How Exchanges Stage the Illusion of Deep Liquidity
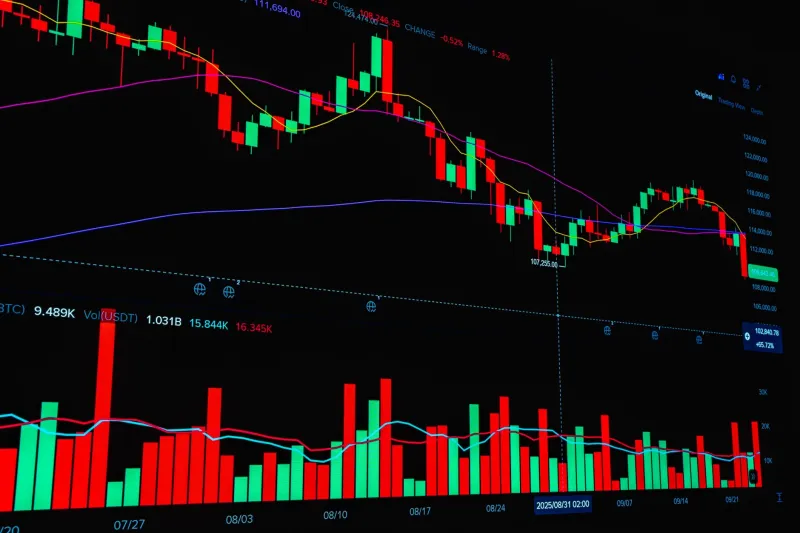
For most retail traders, the logic seems airtight: a high-volume exchange means tighter spreads, faster fills, and less slippage. Volume, in this view, is a proxy for trustworthiness. The higher the number, the safer the venue. It is a reasonable assumption — and it is frequently wrong.
A significant portion of the trading volume reported across major cryptocurrency exchanges is not the product of independent buyers and sellers reaching genuine agreement on price. It is manufactured. Understanding how that manufacturing works, and why exchanges have every incentive to perpetuate it, is essential for any US investor serious about protecting capital at the point of execution.
How Wash Trading Inflates the Numbers
Wash trading — the practice of simultaneously buying and selling the same asset to generate artificial volume — is illegal in traditional securities markets under the Commodity Exchange Act. Its prohibition in spot crypto markets, however, has historically been far less enforced, particularly for venues operating outside direct US jurisdiction.
The mechanics are straightforward. An exchange, a market-making firm with a preferential arrangement, or even a coordinated group of accounts executes matched trades against itself. No economic value changes hands. No genuine price discovery occurs. Yet the reported volume climbs, the exchange rises in third-party rankings, and unsuspecting traders interpret the activity as evidence of deep, reliable liquidity.
Academic research has repeatedly confirmed the scale of the problem. Studies published in peer-reviewed finance journals have estimated that wash trading accounts for a substantial fraction — in some analyses, the majority — of reported volume on certain unregulated platforms. Even on venues that have undergone compliance improvements, residual inflation remains difficult to fully eliminate.
Circular Flows and Internal Market-Making
Wash trading is the most visible form of volume inflation, but it is not the only one. Circular flows — where assets move between affiliated wallets, subsidiary accounts, or partnered entities in patterns designed to register as independent trades — serve the same function with greater operational complexity.
Some exchanges also maintain proprietary trading desks that operate alongside retail order flow. When those desks trade primarily against each other or against internal accounts, the resulting volume appears on public dashboards as market activity. From the outside, it is indistinguishable from genuine third-party trading. From the inside, it is a controlled environment engineered to maintain favorable metrics.
Creative reporting conventions compound the problem. Certain exchanges count both sides of a single transaction toward their volume totals, effectively doubling every trade's statistical footprint. Others include internal transfers, settlement flows, or liquidity-provider rebate transactions in their headline figures. None of these practices are necessarily fraudulent in isolation, but collectively they produce volume numbers that bear only a loose relationship to the execution environment a retail trader will actually encounter.
What Real Liquidity Actually Looks Like
Genuine liquidity is not a headline number. It lives in the order book, and it reveals itself under pressure.
The most reliable indicator of true depth is the bid-ask spread at various size thresholds. A market may quote a tight spread for a 0.1 BTC order and widen dramatically for a 5 BTC order. Examining the order book at multiple size levels — not just the best bid and offer — reveals how quickly available liquidity degrades as order size increases. Exchanges with genuine depth maintain relatively stable spreads across meaningful order sizes. Exchanges with inflated volume often show thin books that collapse the moment a moderately sized order arrives.
Market impact analysis offers another diagnostic tool. Traders who maintain records of their own execution quality over time can compare the price they expected to receive against the price they actually received. Persistent, systematic shortfalls — slippage that consistently exceeds what the quoted spread would predict — are a reliable signal that the order book is shallower than reported volume implies.
Third-party analytics platforms that monitor on-chain settlement activity provide an additional check. Because blockchain records are immutable, actual settlement flows can be compared against reported trading volumes. Exchanges where reported volume dramatically exceeds on-chain settlement activity warrant scrutiny.
The Regulatory Dimension for US Traders
The CFTC and SEC have both signaled increased attention to wash trading and market manipulation in digital asset markets. The Commodity Exchange Act's anti-manipulation provisions apply to certain crypto derivatives, and the agencies have pursued enforcement actions against exchanges and individuals engaged in artificial volume generation.
For US traders, this creates a secondary risk beyond poor execution. Participating — even unknowingly — in markets where manipulation is endemic can complicate tax reporting, create record-keeping inconsistencies, and, in extreme cases, raise questions about the integrity of reported cost basis and holding periods. An exchange environment where prices are being artificially influenced is one where your reported transaction data may not reflect genuine market conditions.
A Practical Verification Framework
Before committing meaningful capital to any exchange, disciplined investors should apply a structured evaluation process:
Examine order book depth at multiple size tiers. Most professional trading interfaces allow users to view cumulative order depth at 0.5%, 1%, and 2% price increments. Compare this depth against the exchange's reported daily volume. A mismatch between thin book depth and high reported volume is a warning sign.
Use multiple data sources. Cross-reference reported volume across at least three independent analytics platforms. Significant discrepancies between sources often indicate that the exchange's self-reported figures are not being validated by external observation.
Test with small orders first. Before executing at scale, place test orders of varying sizes and document the actual fill prices relative to quoted prices. Real-world slippage data is more informative than any dashboard statistic.
Prioritize regulated venues. Exchanges registered with US regulators and subject to audit requirements face greater accountability for their reported metrics. While regulation does not guarantee accuracy, it creates consequences for deliberate misrepresentation that unregulated venues do not face.
Monitor settlement transparency. Platforms that publish on-chain settlement data or submit to third-party proof-of-reserves audits provide a baseline of verifiability that self-reported volume figures alone cannot offer.
The Discipline of Skepticism
Cryptocurrency markets reward investors who question what they are told. Volume figures, like any self-reported metric in an industry still developing its regulatory infrastructure, should be treated as a starting point for inquiry rather than a conclusion.
The investors who navigate this environment most effectively are not those who find the exchange with the highest headline number. They are the ones who understand that liquidity is a dynamic property of real order flow — and that real order flow must be verified, not assumed.