Verified or Vanished: How KYC Mandates Are Quietly Redrawing the Map of American Crypto Trading
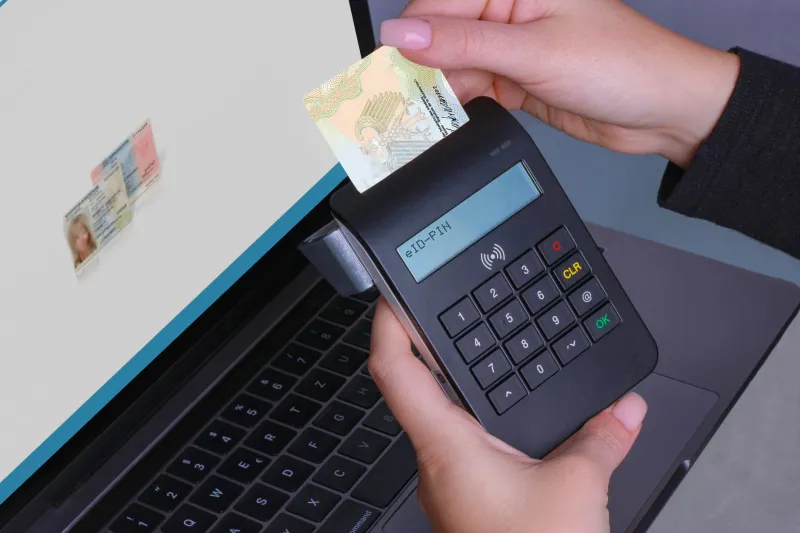
For most Americans opening a crypto trading account today, the process feels familiar: upload a government-issued ID, submit a selfie, wait for approval. It resembles opening a bank account more than it resembles the decentralized financial revolution that early adopters envisioned. That resemblance is not accidental. Know Your Customer — KYC — requirements have become the central mechanism through which regulators are asserting control over an industry that was, by design, resistant to it.
What began as a compliance checkbox has evolved into a structural force reshaping where Americans trade, what they can trade, and at what cost to their financial privacy.
The Regulatory Architecture Behind KYC
KYC requirements in the United States do not emerge from a single statute. They are the product of layered obligations drawn from the Bank Secrecy Act of 1970, the USA PATRIOT Act of 2001, and increasingly assertive guidance from FinCEN — the Financial Crimes Enforcement Network. Exchanges operating as Money Services Businesses are required to collect and verify customer identity information, monitor transactions for suspicious activity, and report findings to federal authorities.
The Financial Action Task Force's Travel Rule — which mandates that identifying information accompany crypto transfers above a certain threshold — has added another layer of complexity. For US-based platforms, compliance is not optional. For traders, the implications are significant.
What this means in practice is that virtually every regulated exchange accessible to American investors now operates as a data collection point. Name, address, Social Security number, and in some cases employment and income information are standard intake requirements. For traders accustomed to the pseudonymous nature of blockchain transactions, this represents a fundamental tension at the heart of modern crypto participation.
The Fragmentation Effect
KYC compliance has not simply inconvenienced traders — it has fragmented the US crypto landscape into distinct tiers.
At one end sit the fully regulated, publicly traded or registered exchanges that offer the broadest asset selection, institutional-grade custody, and seamless fiat on-ramps. These platforms collect extensive personal data, cooperate with law enforcement subpoenas, and in some cases proactively share transaction data with the IRS under existing reporting frameworks. For many retail investors, this is an acceptable trade-off — particularly those whose primary concern is convenience and regulatory legitimacy.
At the other end of the spectrum are decentralized exchanges — DEXs — and peer-to-peer platforms that, by their technical architecture, do not custody funds or verify identity in the traditional sense. These platforms have attracted traders who prioritize autonomy over convenience. However, regulatory pressure is increasingly reaching into this space as well. The Treasury Department's sanctions against Tornado Cash in 2022 signaled that even smart contract protocols are not beyond the reach of US enforcement action, creating legal uncertainty for Americans who interact with non-custodial infrastructure.
Between these poles lies a fragmented middle ground: offshore exchanges that accept US customers with varying degrees of KYC rigor, platforms that have geofenced American users entirely to avoid regulatory exposure, and emerging compliant privacy solutions that attempt to satisfy both regulators and privacy-conscious traders.
What Traders Are Actually Giving Up
The practical consequences of comprehensive KYC extend beyond the inconvenience of document submission. Financial privacy researchers and civil liberties advocates have raised substantive concerns about the data security implications of centralized identity repositories.
When a major exchange holds verified identity records linked to wallet addresses and transaction histories for millions of Americans, that database becomes an attractive target. The industry has not been immune to breaches — several prominent platforms have experienced data incidents that exposed customer information to bad actors. For a trader whose identity is now permanently linked to a blockchain address, such a breach carries consequences that extend well beyond a compromised password.
There is also the question of secondary use. Information collected for compliance purposes does not necessarily stay within compliance channels. Tax reporting obligations, law enforcement requests, and in some jurisdictions, civil litigation subpoenas have all created pathways through which KYC data has traveled beyond its original purpose.
The Emergence of Compliant Privacy Solutions
In response to these pressures, a segment of the industry has invested in privacy-preserving compliance technology. Zero-knowledge proof systems — cryptographic methods that allow a party to verify a claim without revealing the underlying data — are being actively developed as a potential bridge between regulatory requirements and user privacy.
The concept is straightforward in theory: a trader could prove to a regulated platform that they are a verified US resident without transmitting the actual documents or personal data that create downstream privacy risks. Several blockchain projects are actively building this infrastructure, though widespread adoption at the exchange level remains nascent.
For US investors evaluating their options today, this technology offers promise but not yet a practical solution. In the near term, the choice remains largely binary: accept comprehensive identity verification in exchange for access to regulated platforms, or accept the legal ambiguity and technical complexity of less regulated alternatives.
The Regulatory Trajectory
There is little indication that KYC requirements in the United States will ease in the near term. The SEC's expanded enforcement posture, combined with Congressional interest in comprehensive crypto legislation, suggests that identity verification requirements are more likely to broaden than contract.
Proposed legislation in recent Congressional sessions has included provisions that would extend KYC-style obligations to a wider range of crypto service providers, including potentially certain DeFi protocols and non-custodial wallet providers. Whether such provisions survive legislative negotiation remains uncertain, but the directional pressure is clear.
For exchanges like AliasCrypt operating in this environment, the imperative is to build compliance infrastructure that satisfies regulatory requirements without unnecessarily expanding the collection or retention of customer data beyond what those requirements demand. Minimizing data exposure while maintaining full legal compliance is not a contradiction — it is increasingly a competitive differentiator.
Navigating the Trade-Off Intelligently
For American traders, the practical guidance is to approach exchange selection with the same analytical rigor applied to asset selection. Evaluate not only the trading features and fee structure of a given platform, but its data retention policies, breach response history, and the legal jurisdiction governing its operations.
Understood correctly, KYC compliance is not simply a regulatory burden — it is a disclosure. When you verify your identity on a platform, you are entering into an implicit agreement about how that information will be used, stored, and potentially shared. Reading that agreement carefully is no longer optional for the serious investor.
The identity verification landscape in American crypto is not going to simplify. Traders who understand its architecture — and make deliberate choices accordingly — will be better positioned than those who treat KYC as a frictionless formality.